Haivision Systems Inc. (OTCPK: HAIVF/HAI.TO) – Q3 2025 Earnings
- Earnings Release Date: Sep. 10, 2025
- Stock Price: $4.65
- Market Cap: $131.8 million
- Q3 2025 sales of C$35.0 million vs C$30.6 million in the prior year
- Q3 2025 EPS of C$0.01 vs C$0.01 in the prior year
Press Release vs Call Transcript Comparison
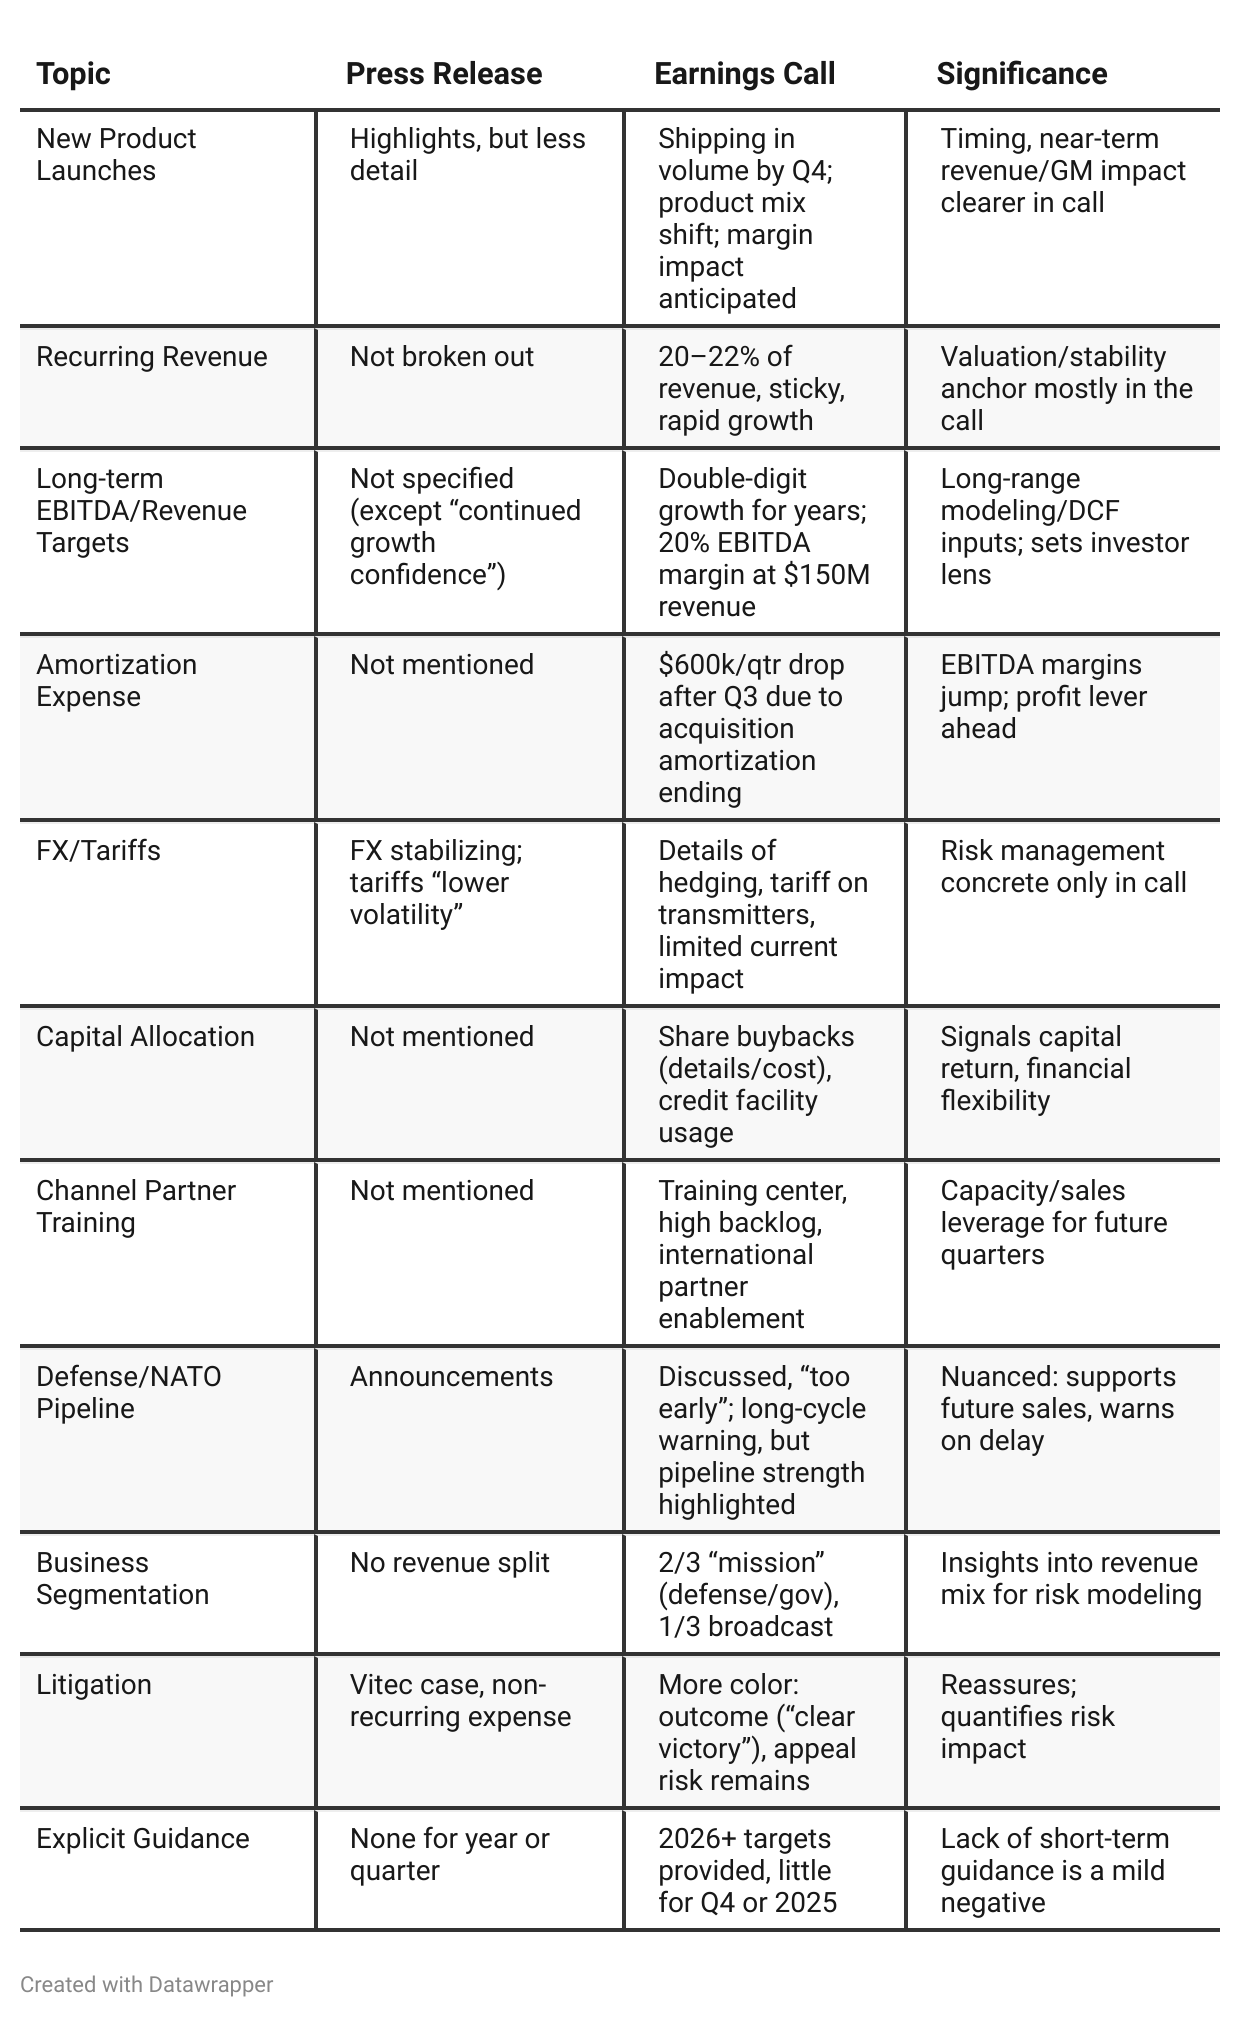
- Earnings call more forward-looking: While the press release trumpets recent contract wins and product launches (good for headlines/PR), the earnings call lays out explicitly how and when these will impact the financials, giving investors more anchor points for modeling.
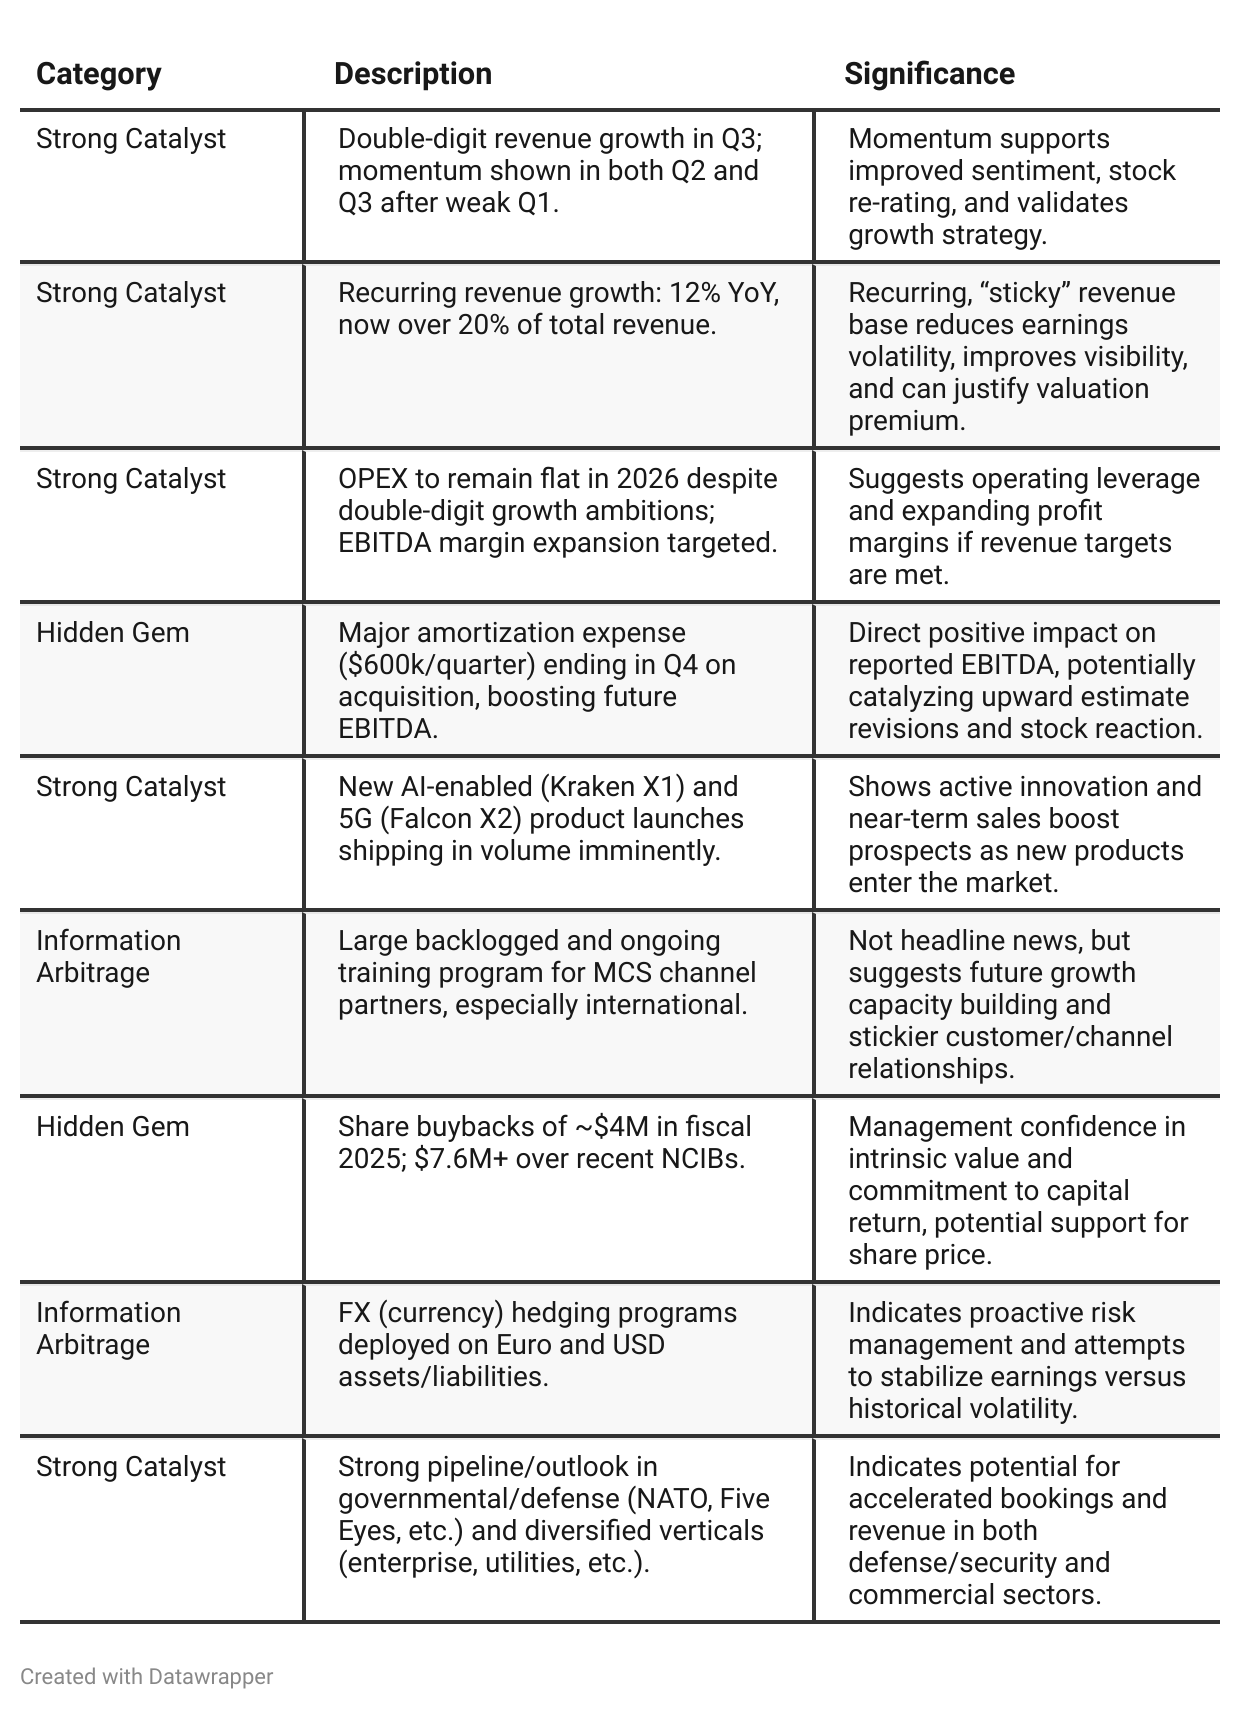
- Recurring revenue is understated in PR: The earnings call’s focus on sticky maintenance and SaaS contracts bolsters the investment thesis around revenue stability and, potentially, premium valuation versus purely project-based peers.
- Margin improvement drivers explained in call: The press release notes margin pressure but does not address when/how it gets resolved. The call explains expense normalization, the one-time legal hit, and the coming drop in amortization.
- Risks and lumpiness acknowledged in call, not PR: The call’s candor about contract lumpiness, sales cycle timing, and tariff risk provides a more balanced/realistic risk assessment that a PR alone would lack.
- Shareholders rewarded via NCIB: Share buybacks (not surfaced by PR) are a positive for capital return and indicate the company sees share undervaluation.
- International partner enablement is a growth lever: Not mentioned in the PR, but the training investment (mentioned on the call) could drive future revenue acceleration as the channel is activated abroad.
- Guidance is conservative and long-term: The lack of Q4/annual guidance in both documents may frustrate short-term investors, but the doubling down on double-digit, “$150M at 20% EBITDA margin” for mid-term “sets the bar” for institutional models.
Positive Insights